In the basement of a Boise, Idaho, dental office in 1978, four engineers founded what would become one of America's semiconductor giants. Ward Parkinson, Joe Parkinson, Dennis Wilson, and Doug Pitman started Micron Technology as a modest design consultancy, backed by local investors — including potato magnate J.R. Simplot.
By 1983, they had achieved a technological breakthrough: producing chips roughly half the size of Japan's leading products. Nearly five decades later, that same company has made a decision that crystallises artificial intelligence's profound impact on hardware economics.
💡 AI memory hunger is forcing manufacturers to abandon entire market segments.
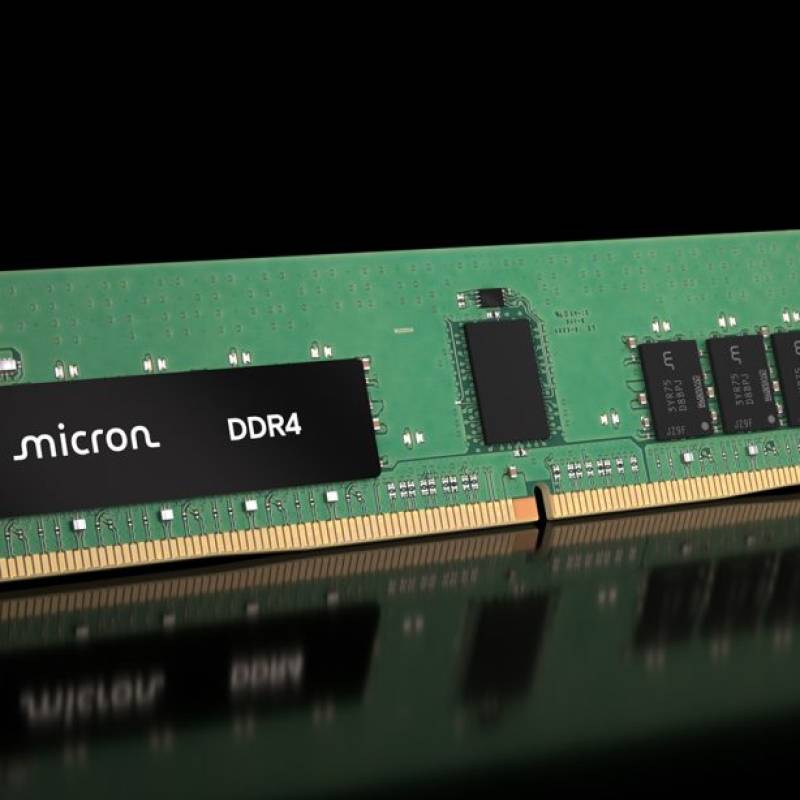
On December 3, 2025, Micron announced it would completely exit the consumer memory market, discontinuing its 29-year-old Crucial brand by February 2026.
💬 "The AI-driven growth in the data centre has led to a surge in demand for memory and storage. Micron has made the difficult decision to exit the Crucial consumer business to improve supply and support for our larger, strategic customers in faster-growing segments."
— Sumit Sadana, Micron's Executive Vice President & Chief Business Officer
The translation is clear: data centres running AI workloads will pay substantially more for memory than individual consumers ever could, and Micron's fabrication capacity cannot serve both markets simultaneously.
This announcement represents both a business decision and a watershed moment — revealing how AI memory hunger demands are restructuring global semiconductor supply chains and forcing manufacturers to make stark choices about which customers "deserve" access to finite production capacity.
📈 The Economics Driving AI Memory Hunger
Micron's withdrawal reflects hard economic realities. As the world's third-largest DRAM producer with approximately 20% of global market share, the company sits between South Korean giants:
- 🇮🇰 Samsung Electronics — 43% global DRAM share
- 🇮🇰 SK Hynix — 35% global DRAM share
- 🇺🇸 Micron Technology — ~20% global DRAM share
Together, these three control roughly 95% of worldwide DRAM production — an oligopoly now facing unprecedented demand from AI infrastructure builders.
The margin differentials tell the story. Consumer RAM modules compete in volatile retail markets with razor-thin profitability. Enterprise contracts for high-bandwidth memory (HBM) used in AI accelerators and DDR5 modules for data centre servers deliver:
- ✅ Substantially higher average selling prices
- ✅ Multi-year commitments
- ✅ Predictable, stable demand
💰 Key Figures: Micron reported record fiscal 2025 revenue of US$37.38 billion — nearly 50% year-over-year growth — with data centre and AI applications accounting for 56% of total revenue.
Consumer memory prices have surged accordingly. DRAM spot prices increased 172% year-over-year as of Q3 2025, with retail prices for 32GB DDR5 modules jumping 163–619% in global markets since September 2025. Component suppliers report paying US$13 for 16GB DDR5 chips that cost just US$7 six weeks earlier — increases sufficient to eliminate entire gross margins for third-party brands.
🔌 Consumer Market Restructuring Amid AI Memory Hunger
Micron's exit fundamentally alters the consumer memory landscape. Third-party brands — including Corsair, G.Skill, Kingston, and ADATA — source their DRAM chips from the major manufacturers. With Micron withdrawing entirely, these vendors must now compete more aggressively for allocation from Samsung and SK Hynix, both of which are simultaneously prioritising HBM production for AI accelerators.
Supply chain constraints are already materialising beyond DRAM:
- 🔴 NAND flash wafer contract prices increased over 60% in November 2025
- 🔴 GDDR6 shortages inflated prices by approximately 30% as manufacturers shift to GDDR7
- 🔴 Hard drive manufacturers raised prices 5–10%, citing limited supply
⚠️ Warning for Consumers & Small Businesses: Product availability may become increasingly constrained during peak demand periods. Reduced direct supplier participation may compress product differentiation and limit the competitive pricing dynamics that previously benefited buyers.
🌎 The Broader Industry Realignment
Micron's consumer exodus signals a structural transformation rather than a temporary reallocation. The AI infrastructure boom differs fundamentally from previous technology transitions. Personal computing, internet expansion, and mobile devices created sustained memory demand over decades with gradual capacity adjustments.
AI infrastructure deployment compresses that timeline dramatically — hyperscale operators are committing hundreds of billions in data centre construction over just a few years.
📊 Market Projections:
• Data centre semiconductor TAM: US$209 billion (2024) → projected ~US$500 billion by 2030
• GPU revenue: US$100 billion (2024) → forecast US$215 billion by 2030
Memory architecture evolution compounds the challenge:
- 🎯 AI training workloads increasingly require HBM3E modules for superior bandwidth and power efficiency
- 🎯 AI inference workloads demand DDR5 with tight latency specifications
- 🎯 Automotive applications adopting zonal architectures require multi-gigabyte DRAM configurations
The manufacturing response reflects these priorities:
- 🔧 Samsung is advancing 1c DRAM production, planning HBM4 mass production in 2025, and phasing out DDR4 entirely
- 🔧 Micron began mass production of DRAM using Extreme Ultraviolet (EUV) lithography in 2025
- 🔧 SK Hynix is focusing development resources on HBM and advanced LPDDR solutions
🏢 What This Means for Enterprise Buyers
Enterprise procurement teams face their own significant challenges as memory markets restructure. Memory represents 10–25% of bill-of-materials costs for typical servers and commercial PCs. Price increases of 20–30% in memory components translate to 5–10% increases in total system costs — compounding into millions in additional expenditure for organisations procuring at scale.
Strategic responses include:
- ✅ Forward purchasing agreements
- ✅ Establishing stronger direct relationships with manufacturers
- ✅ Diversifying vendor partnerships
❓ Critical Questions Ahead
Micron's consumer market exit raises fundamental questions for the entire industry:
- 🔴 Will Samsung and SK Hynix maintain consumer product lines, or will similar capacity pressures force comparable reductions?
- 🔴 If consumer memory becomes primarily a third-party brand market, what happens to product innovation and competitive pricing?
- 🔴 Could supply chain disruptions affecting either remaining major manufacturer have an outsized impact on global consumer product availability?
💡 Broader implications extend to technology accessibility. If memory pricing remains elevated or availability constrained for consumer products, the costs of personal computing and small business infrastructure increase accordingly — potentially widening digital divides.
Micron's decision crystallises artificial intelligence's role as a transformative force reshaping not just software, but the fundamental economics of hardware manufacturing. The Crucial brand's retirement after 29 years marks the end of an era when memory manufacturers could serve both consumer and enterprise segments simultaneously and profitably.
For the broader technology ecosystem, hunger for AI memory has become the semiconductor industry's dominant growth driver — commanding resources at levels that fundamentally alter which markets manufacturers choose to serve.
 OpenAI - ChatGPT, Sora
 Google - Gemini, Nano Banana
 Anthropic - Claude
 xAI - Grok
 Deepseek
 Alibaba - Qwen
 ByteDance - Doubao
 All Models
 Enterprise Plans
 AI Application Development
 AI Translator API
 AI SEO/GEO Service
 GEO-Optimized PR Service
 Web Scraping Service
 OpenClaw
 Top AI Tools
 Top AI Robots
 Log in